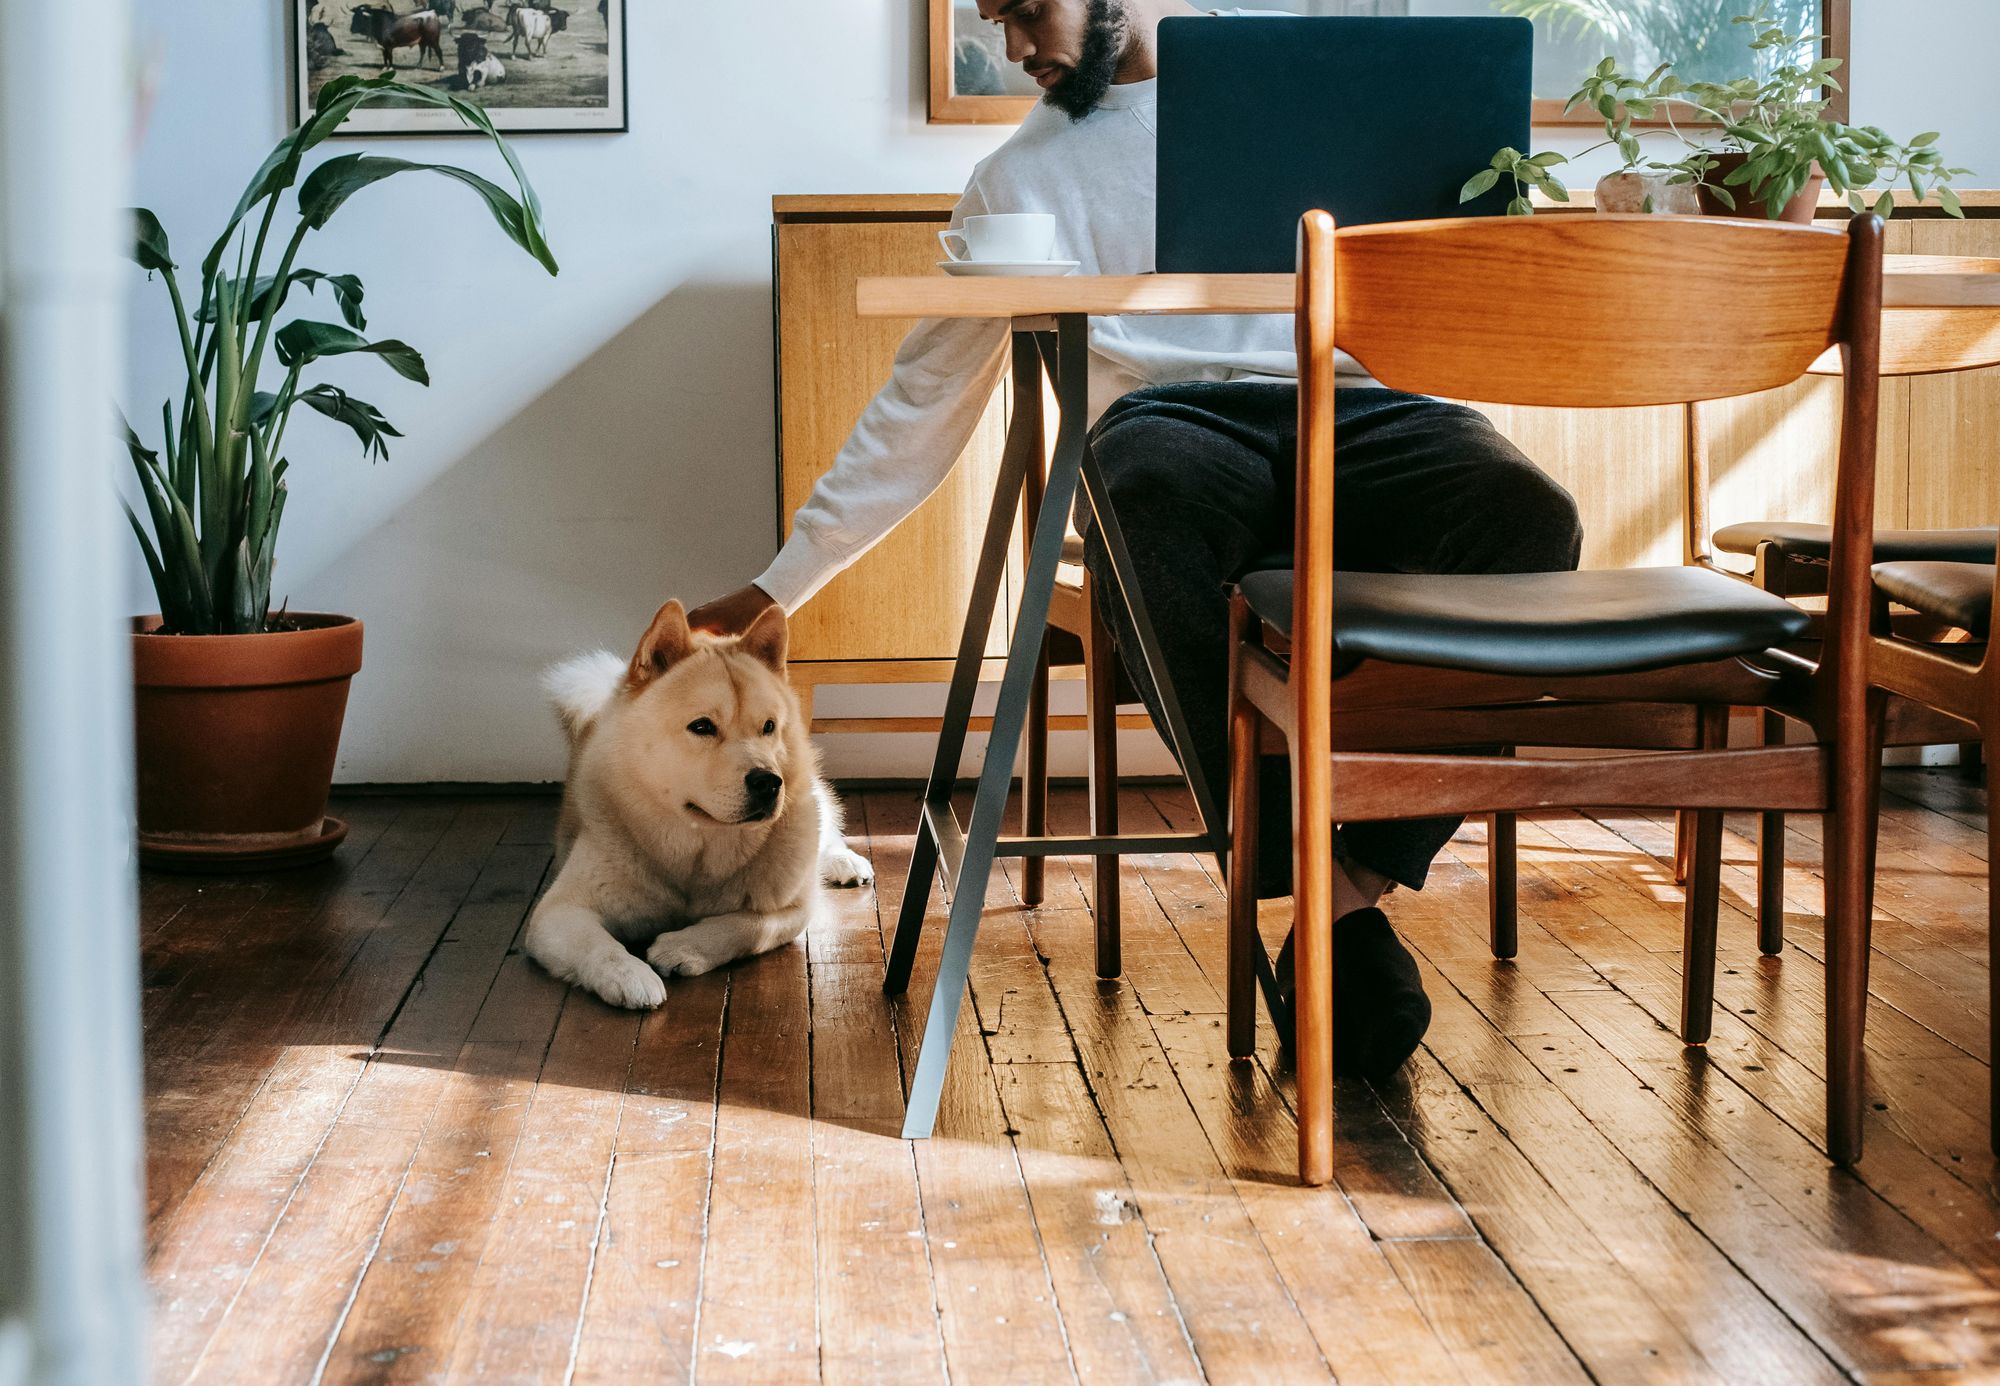
For many entrepreneurs it's perfectly normal by now: you work from home or at the office, and your dog is lying somewhere nearby. Under your desk, on a rug, or strategically right in your path. He's there all day, he's part of your routine and he makes your working day that little bit better. A colleague of sorts, just without the meetings and with much better energy. So why couldn't you simply put him on the business?
The idea sounds appealing, but from a tax point of view it's a lot less straightforward. Where you see a loyal office buddy, the Tax Authority (Belastingdienst) mainly sees a private expense. In most cases it falls apart on the demonstrable business function. Unfortunately, a dog often has one. Because however nice it is that your dog keeps you calm, that he's good company during your working day or that he's a customer magnet, those are all benefits to you as a person, not to your business. The Tax Authority doesn't look at feelings, it looks at necessity. Is the dog essential to running your business? If not, he quickly ends up in the private category.
That means costs such as food, vet bills, the purchase price and training are in principle not deductible. Not even if you take him to the office every day and pay for everything neatly from your business account. There has to be a clear business reason behind it, and that only applies in specific situations. Think of a guard dog protecting business premises, or a working dog with a specific function. In situations like those, the dog isn't just pleasant company but a functional part of how your business operates.
Even so, plenty of entrepreneurs get this wrong. Their reasoning is that their dog is always there while they work, so it must be a business matter. But being present is not an argument. The Tax Authority takes an objective view: could your business function (properly) without this dog? If the answer is 'no', it means it isn't a business matter.
Still wondering whether your situation is different? There's a simple test you can apply: would you incur these costs even if you didn't have a business? If the answer is 'yes', there's a good chance the Tax Authority will see them as private too.
The conclusion is pretty clear. An office dog is great for your job satisfaction and perhaps even your productivity, but for tax purposes he is, in most cases, simply private. Only if your dog plays a demonstrable role in your business is there room to treat the costs as business costs. Until then: enjoy your dog next to your desk, but keep him out of your books!